After the Sale: Recovering a Surplus from an Unredeemed Pledge
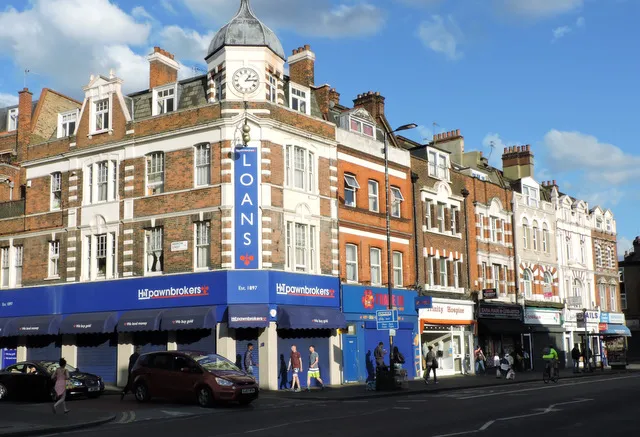
Photo: Thomas Nugent , CC BY-SA 2.0, via Wikimedia Commons
Why a surplus can arise
Pawnbroking is a secured lending arrangement. A customer pledges an item in return for a loan, and the item remains the broker’s security until the agreement is settled. If the customer does not redeem the pledge within the agreed period, the broker may sell it in accordance with the terms of the agreement and the applicable regulatory framework.
Where the sale price exceeds the amount properly due under the agreement, the difference is commonly described as a surplus. In straightforward terms, the calculation starts with the sale proceeds and deducts the outstanding loan, contractual interest and any charges permitted by the agreement and applicable rules. What remains should be accounted for and, where a surplus is due, returned to the customer.
The principle is simple. The pledge is security for a debt, not a transfer of the customer’s entire interest in the item. A sale should not become an unexpected windfall for the broker at the customer’s expense. That is why surplus handling sits firmly within the fair treatment of customers and why it deserves careful attention from every pawnbroking business in 2026.
The calculation should be transparent
A surplus figure is only meaningful if the customer can see how it was reached. A clear statement should identify the item sold, the date of sale, the gross sale proceeds, the amount outstanding at the point of sale, the interest and charges applied, and the resulting surplus or shortfall. Where a shortfall arises, the position should also be explained plainly.
Members should avoid relying on broad references to “costs” without explanation. Any deduction should be traceable to the pawn agreement and to the rules that govern the sale. Consumers are entitled to ask for a breakdown, and a well-run counter should be able to provide one without difficulty.
Good practice also means keeping the calculation consistent with the records. If the ticket, the ledger and the sale record do not agree, the customer’s confidence will be undermined, and the broker’s ability to demonstrate compliance will be weakened.
Notification is part of the obligation
A surplus does not become fair simply because it is recorded internally. The customer should be told about it in a clear and timely way. Notification expectations should be built into the firm’s processes rather than left to individual memory or informal practice.
A useful notification will explain that the item has been sold, set out the calculation, state the amount of any surplus, and explain how the customer can claim it. It should also give a contact point and a reasonable route for raising questions. Where the customer has moved or changed contact details, the firm should be able to show what reasonable steps it took to make contact using the information available.
The method of payment should be secure and documented. Whether the surplus is paid by bank transfer or another agreed method, the firm should retain evidence of the payment and of the customer’s instructions. Cash handling should follow the firm’s normal controls, with a clear audit trail.
Record-keeping discipline for members
Surplus handling is a record-keeping discipline as much as a customer service issue. At minimum, members should be able to show:
- the identity of the customer and the pledge ticket reference;
- the item sold and the date of sale;
- the sale proceeds and the basis on which the item was sold;
- the outstanding balance, interest and permitted charges;
- the surplus calculation and the amount due;
- the date and method of notification;
- the date, method and proof of payment; and
- any customer query and the firm’s response.
These records should be retained in line with the firm’s legal and regulatory obligations and should be available to those responsible for compliance oversight. A simple surplus register, reviewed periodically, can help identify outstanding amounts and prevent cases from drifting.
Members should also consider how staff are trained. Counter staff need to recognise when a surplus has arisen, explain the position without jargon, and escalate queries promptly. A consistent script can help, but it should not replace a clear understanding of the underlying calculation.
If you believe a surplus is owed
Consumers who receive notice of a sale and believe a surplus remains outstanding should act promptly. Start by contacting the pawnbroker in writing, quoting the pledge ticket reference and the date of sale. Ask for a written statement showing the sale proceeds, the amount outstanding, the deductions applied and the surplus calculation.
Keep copies of the ticket, correspondence and any payment records. If the response is unclear, ask for the specific point to be explained rather than accepting a general assurance. Where the firm is a member of a trade association, check whether its complaints procedure offers an additional route for review.
If the matter cannot be resolved, use the firm’s formal complaints process. If the firm is regulated by the Financial Conduct Authority and the complaint remains unresolved, the customer may be able to refer it to the Financial Ombudsman Service. Time limits apply, so it is important not to delay once the issue has been raised.
Consumers should also be wary of any request to pay a fee before a surplus is released. A genuine surplus belongs to the customer, and a legitimate process should not depend on an advance payment to a third party.
A fair outcome, clearly evidenced
The surplus question is ultimately about fairness and evidence. A broker that calculates carefully, notifies clearly and records thoroughly is better placed to demonstrate compliance and to maintain consumer confidence. A customer who understands the calculation is better placed to hold a business to account.
In 2026, with continuing scrutiny of consumer credit and fair treatment, surplus handling should not be treated as an administrative afterthought. It is a visible test of how a pawnbroking business manages other people’s property and money. Handled well, it reinforces the principle at the heart of responsible pawnbroking: the loan is repaid, the customer’s interest is respected, and any balance due is returned without unnecessary friction.